September 20, 2026 · 16 min read
Before Capital Moves: Euthyna and Governed Disbursement
A plain-English guide to governed capital disbursement: how Euthyna turns project evidence, rules, approvals, and exceptions into a defensible answer about whether the next release is eligible to proceed.
Euthyna · Capital Governance · Project Finance · Assurance · Risk Management
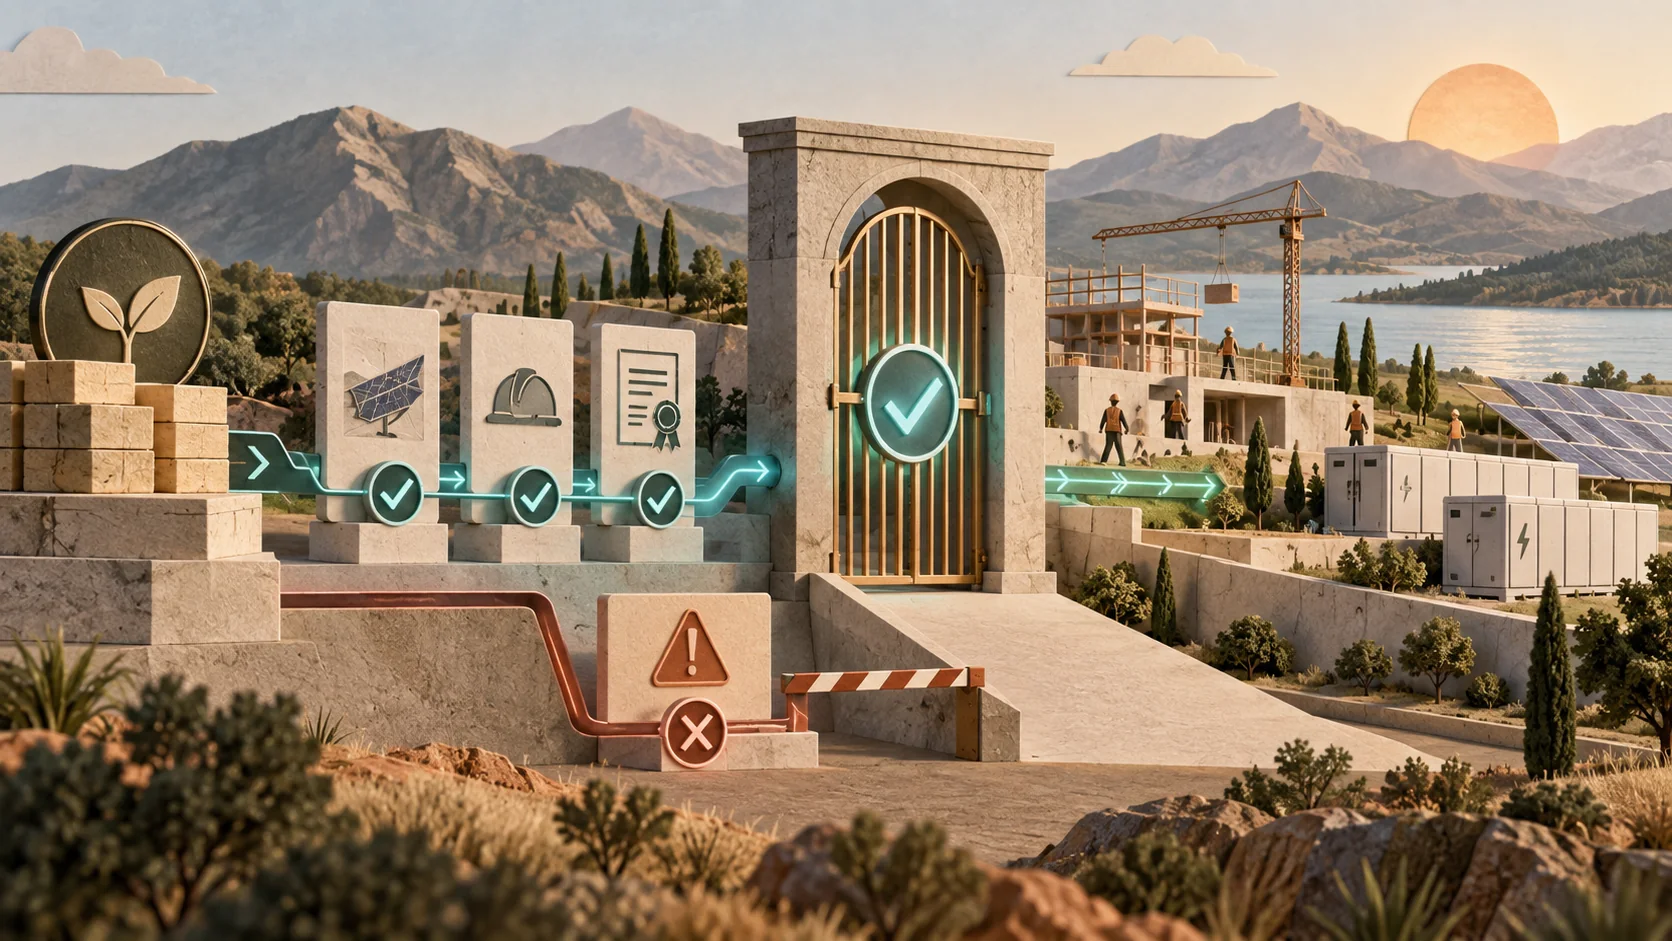
Capital progresses when the approved conditions are satisfied; an unresolved exception holds the next stage without stopping people from fixing it.
A company can approve a project budget on Monday and still be unable to answer a more important question on Friday: should the next portion of that money move now?
Those are different decisions. A budget authorizes a plan. A disbursement releases capital against that plan. Between the two sits the difficult work of proving that the project has reached the right point, the required evidence is reliable, the right people have approved, and no unresolved problem should stop the release.
That middle layer is where Euthyna operates.
Euthyna is an assurance and governance layer for staged investment. It does not hold money, provide a bank account, process a payment, or decide on its own where an organization should spend. It evaluates whether the conditions defined by the organization have been satisfied, records the reasoning, and produces a defensible answer about whether a capital action is eligible to proceed.
To understand why that matters, it helps to start with the ordinary business concepts underneath it.
Governance, in plain language
Governance is the set of rules, responsibilities, checks, and records that make an important decision accountable.
In a project, governance answers questions such as:
- Who is allowed to approve the plan?
- What must be true before work moves to the next stage?
- What evidence is required, and who is qualified to verify it?
- Can the person who submitted the evidence also approve the release?
- What happens when an inspection fails or the project changes?
- How will the organization later explain why it made the decision it made?
Governance is not the same as management. Management gets the work done. Governance establishes how consequential decisions are made, who may make them, what they must rely on, and how they remain reviewable.
Good governance does not eliminate human judgment. It gives that judgment boundaries and makes its use visible. It also prevents a decision from becoming valid merely because a senior person said yes in an email.
What capital disbursement means
Capital disbursement is the release or making available of money that has already been committed to a purpose.
Large projects rarely receive their entire budget in one transfer. A construction project, factory expansion, energy installation, or technology modernization may be funded in stages. Each stage can be called a draw, tranche, or milestone payment. The vocabulary changes by industry, but the basic idea is the same: capital is released as the project earns the right to receive the next amount.
The organization holding the funds might be a project owner, lender, investment vehicle, treasury team, escrow provider, or custodian. Its bank or payment platform performs the actual transfer. The disbursement process determines whether the prerequisites for that transfer have been met.
That distinction is central to Euthyna:
Euthyna decides and records eligibility. An authorized external financial system moves the money.
One project to follow from beginning to end
Consider a fictional but realistic example. Harbor Ridge Energy is developing a $120 million solar-and-battery facility. The project is financed by its owner and a lending group. The approved capital plan divides the work into five milestone-based tranches:
- Site acquisition, permits, and mobilization
- Long-lead equipment manufacture and delivery
- Foundations, electrical infrastructure, and equipment installation
- Testing and grid commissioning
- Final completion and closeout
We will follow the third tranche: a $24 million release tied to equipment delivery and completion of the principal foundations.
The parties agree in advance that this tranche requires an independent engineer’s completion certificate, equipment delivery records, invoices reconciled to the approved allocation, confirmation that critical permits remain valid, resolution of any blocking change orders, and approval from both the owner’s project-finance lead and the lender’s authorized representative.
They also require separation between roles. The contractor can submit evidence. The independent engineer can verify construction progress. The project-finance lead and lender can approve. One person cannot quietly perform all three jobs.
These are business rules chosen by the parties responsible for the capital. Euthyna does not invent them.
How organizations normally disburse project capital
Without a dedicated governance layer, the process usually spans several systems and a great deal of human coordination.
The contractor submits a draw request. The project team gathers invoices, photographs, progress reports, inspection certificates, delivery receipts, and change-order records. A project-management system contains schedule status. A document repository holds reports. The ERP contains purchase orders, invoices, and budget balances. Approvals arrive through workflow tools, email, electronic signatures, or meeting minutes. Finance assembles a release packet, checks it, and sends an instruction to treasury, a lender, or another authorized payment party.
None of those systems is necessarily defective. Each may perform its own job well. The difficulty is that the release decision depends on facts spread across all of them.
For Harbor Ridge’s third tranche, someone must establish that the engineer’s certificate applies to the correct milestone, the delivered equipment matches the approved scope, the invoices fit within the current plan version, both required approvers acted, and a newly opened change order does not block the draw. Someone must also preserve enough of that reasoning for a board, lender, auditor, or regulator to inspect later.
In many organizations, that proof exists only as a packet assembled at a moment in time. Its strength depends on the people assembling it, the versions they found, the checks they remembered, and the clarity of their records.
What can go wrong
Capital can move too early even when nobody is dishonest. The process may simply be fragmented.
An inspection report can be missing while a progress dashboard still shows the milestone as complete. An invoice can match the original budget but not the latest approved change order. Two approvals can appear valid even though both came from people whose roles should have been separated. A contractor’s own progress report can be treated as equivalent to an independent engineer’s certificate. A blocking exception can live in a project log that finance never sees. An approver can rely on a document that was replaced the next morning.
The reverse can also happen. Capital that should move can remain delayed because nobody can determine which evidence is authoritative, which approval is still pending, or who owns the exception. Governance that is vague creates friction as well as risk.
The deepest problem appears later, when someone asks a simple question: “Why was this $24 million release allowed?”
If the answer requires reconstructing email threads, spreadsheet versions, document folders, meeting notes, ERP entries, and people’s memories, the organization has a history of activity but not necessarily a defensible decision record.
What governed capital disbursement means
Governed capital disbursement makes eligibility an explicit, evidence-based decision rather than an implication assembled from scattered activity.
The approved plan defines the amount and purpose of each tranche. The governance policy defines the conditions for eligibility. Evidence is connected to specific completion criteria. Authorized people verify and approve under defined role boundaries. Exceptions and holds are evaluated alongside the positive evidence. The result is a recorded decision that explains which conditions passed, which failed, what inputs were used, and which policy version governed the outcome.
The organization still decides the commercial terms. Human specialists still inspect the work and exercise professional judgment. The ERP still records financial transactions. The project-management system still tracks execution. The bank, treasury platform, custodian, or escrow provider still moves funds.
Governed disbursement adds a reliable answer between those systems:
Is this specific capital release eligible to proceed under the rules the parties approved?
The Harbor Ridge draw without Euthyna
The third-tranche request arrives on a Thursday afternoon. The contractor’s packet includes invoices, delivery receipts, photographs, and a progress report. The project manager believes the foundations are complete. The ERP shows enough remaining budget. One approver replies “approved” by email; the lender’s representative signs a PDF.
Finance notices that the independent engineer’s certificate is not in the shared folder. The contractor says it was uploaded under a different filename. Meanwhile, the project-management system shows an unresolved change order affecting part of the electrical scope. Nobody is certain whether that change should block the entire tranche or only a later payment.
The finance team starts reconciling versions. It asks the project manager which plan is current, asks legal whether the change order is material, checks whether the two approvals satisfy the lending agreement, and waits for the engineer’s certificate. When the missing document arrives, someone rebuilds the draw package and circulates it again.
If the release proceeds, the bank transfer is properly executed and the ERP records it. But the governance proof remains distributed across the packet, inboxes, system histories, and the judgment of the people involved. An auditor reviewing the decision months later must reconstruct the same story.
The same draw with Euthyna
With Euthyna, the parties first bind the third tranche to an approved plan version and a defined set of conditions. The system knows the required evidence categories, the minimum authority expected from each source, the approval quorum, the segregation-of-duties rules, relevant dependencies, and the exceptions that must be clear.
As Harbor Ridge’s evidence arrives, Euthyna records what each artifact claims, where it came from, what milestone criterion it supports, and whether the artifact remains unchanged. A contractor’s progress report is not silently promoted into an independent certification. Both may be valid documents, but they carry different authority and satisfy different requirements.
When the first eligibility evaluation runs, the result is HOLD, not because Euthyna dislikes the project or predicts failure, but because two approved conditions are not satisfied:
- the independent engineer’s certificate is missing;
- the electrical change order is unresolved and is defined as blocking this tranche.
The decision record shows the conditions that passed as well: delivery evidence is accepted, invoices reconcile within the allocation, permits are current, and one of two required approvals has been recorded. People do not have to guess what remains. The hold points directly to the missing proof and open exception.
The engineer then submits the certificate. An authorized verifier confirms it against the foundation criterion. The project team resolves the change order through its approved process, producing a new recorded outcome rather than editing the old problem away. The lender’s authorized representative supplies the second approval. Euthyna checks that the submitter, verifier, and approvers satisfy the required separation of duties.
The same rules are evaluated again. This time every required condition passes. Euthyna records the tranche as eligible and can publish an eligibility signal or certificate to the organization’s authorized external workflow.
Treasury or the lender—not Euthyna—then releases the $24 million through the existing banking process. When confirmation of that external payment returns, it can be reconciled against the eligible tranche. A duplicate, excessive, expired, or otherwise inconsistent payment observation becomes an exception rather than disappearing into the books as an unexplained mismatch.
The practical difference is not that the project has more documents. It is that the relationship among the plan, evidence, rules, approvals, exceptions, decision, and eventual payment remains intact.
The heavy lifting Euthyna performs
Euthyna’s work is easiest to understand as the conversion of scattered project facts into governed proof.
It organizes evidence around decisions
A document merely existing does not prove a milestone. Euthyna connects evidence to the condition it is meant to satisfy and preserves its provenance. It distinguishes the integrity of an artifact—whether the bytes are unchanged—from the authority of its source and the sufficiency of the evidence under the approved rule.
That matters in the Harbor Ridge example. An intact contractor report is still not an independent engineer’s certificate. The first may be useful without satisfying a condition that explicitly requires the second.
It applies deterministic eligibility rules
Euthyna evaluates a closed set of approved conditions. The same plan version, evidence, approvals, exceptions, and policy version produce the same result. Each condition contributes a visible pass or failure to the decision trace.
This is not a black-box risk score and not an AI opinion. The organization can inspect why the tranche is or is not eligible.
It enforces roles and approvals
Approval is more than collecting enough signatures. Euthyna records who acted, under what authority, and whether the required quorum and separation of duties were satisfied. A person cannot become an independent check simply by clicking a second button.
It treats problems as governed work
Missing or contradictory evidence does not vanish, and it does not force the project into a permanent dead end. It creates a clear failure or exception that can be assigned, investigated, remedied, and reverified. Holds protect capital progression while giving the project team a precise route back to eligibility.
Change is handled the same way. An approved plan is not silently rewritten. A material change follows a change-order process and produces a new plan version or an explicit rebinding of affected work. The record shows what changed and which decision used which version.
It preserves an append-only history
Euthyna records governance events in sequence. Earlier events are not overwritten to make the history look cleaner. Corrections, superseding evidence, approvals, holds, resolutions, and new decisions are appended as new facts.
The records are hash-chained and reverified, so altering an earlier event breaks the chain. Because project state is reconstructed from those events, the organization can replay the record and reproduce how a past eligibility decision arose. This is not a claim that every underlying business fact was true; it is a strong record of what was submitted, verified, approved, decided, and later changed.
It keeps execution outside the governance boundary
Euthyna’s strongest positive output is eligibility, not a payment instruction. The organization retains its existing financial controls and execution systems. This separation keeps the governance question—“may this tranche proceed?”—distinct from custody and payment operations.
Why not rely on ERP, accounting, and project-management systems?
Organizations should keep using them.
An ERP is excellent at budgets, commitments, invoices, accounting entries, and financial reporting. A project-management system is excellent at schedules, tasks, dependencies, and progress. A document system stores the reports. Identity and workflow tools manage access and signatures. Banks and payment providers execute transfers.
The governed release decision crosses all of those boundaries. It asks whether a particular combination of financial state, project progress, evidence quality, approvals, dependencies, and open exceptions satisfies a specific policy at a specific moment.
Euthyna does not replace the systems of record. It provides the assurance layer that relates their governed facts to the release conditions, explains the resulting eligibility decision, and preserves that reasoning.
Who defines the rules?
The people accountable for the capital do.
Depending on the project, that may include the owner, lender, investment committee, legal and compliance teams, technical specialists, insurers, or public authorities. They decide what evidence is required, which sources carry enough authority, how many approvals are needed, which roles must remain separate, what tolerances apply, and which exceptions block progression.
Euthyna turns those approved requirements into versioned, testable conditions. It should not manufacture financial, legal, or compliance policy. Nor should a model quietly invent a new threshold during evaluation.
Can humans override the result?
Humans remain responsible for the project and its policy, but a trustworthy governance system cannot offer an invisible “make it green” button.
Authorized people can supply missing evidence, reject or supersede contradictory evidence, approve or reject a change order, resolve an exception after remediation, and amend future rules through the organization’s defined process. If an organization permits an exceptional override, the authority, conditions, and consequences of that act must themselves be governed and recorded.
The important point is that a human action changes the governed inputs or creates an explicit exceptional record. It does not secretly rewrite the prior decision.
Who benefits from this kind of assurance?
Project owners gain a consistent release process and a clearer view of what is blocking progress. Finance and treasury receive an eligibility record tied to the approved plan rather than another informal request. Lenders and investors can see how each release was earned. Boards gain oversight without having to inspect every document themselves. Auditors receive a traceable decision history. Regulators can examine the controls and evidence relevant to their mandate without mistaking Euthyna for the custodian or payment system.
The strongest fit is a project where capital is large, staged, evidence-heavy, and shared across several accountable parties: infrastructure, energy, manufacturing, real-estate development, major modernization programs, public-private projects, and other long-lived investments with milestone or drawdown structures.
Not every purchase needs this machinery. A routine low-value invoice may be governed adequately by existing procurement and accounting controls. The value rises when the cost of a premature, unsupported, or poorly explained release is materially higher than the cost of making the decision process explicit.
Concise FAQ
Does Euthyna hold, custody, or move money?
No. Banks, treasury systems, custodians, escrow providers, or other authorized financial systems hold and transfer funds. Euthyna governs and records whether the defined conditions for a capital action are satisfied.
What happens when evidence is missing or contradictory?
The affected condition does not pass. Euthyna records why, identifies the resulting hold or exception, and preserves the path through remediation, superseding evidence, reverification, and reevaluation. It does not guess that the condition is probably fine.
What makes the audit history trustworthy?
Events are appended rather than edited in place, linked by hashes, and used to reconstruct project state. The record identifies actors, inputs, policy versions, approvals, exceptions, and decision traces. That makes tampering detectable and past decisions reproducible from the recorded facts.
Does Euthyna replace professional judgment?
No. Engineers inspect, finance professionals reconcile, lawyers interpret obligations, and authorized leaders approve. Euthyna makes the required judgment points explicit and ensures the resulting actions are connected to the rules and evidence they relied on.
Does it replace existing financial or project systems?
No. It sits across them as a governance and assurance layer. Existing systems continue to manage the work, books, documents, identity, and payments for which they are responsible.
Proof as a product of the process
The most important difference is easy to state:
Without Euthyna, people and disconnected systems must prove that capital should move. With Euthyna, the governance process itself continuously produces that proof.
That does not make every project risk disappear. It does make the release decision clearer, more consistent, easier to challenge, and far easier to defend after the fact.
For demonstrations and deeper explanations, visit the SK Fintech YouTube channel at @SKFintechLLC. The Euthyna product page also explains the operating boundary, example gate decisions, and ways to evaluate the platform.